Cherry: The Smarter Way to Pay

Screenshots
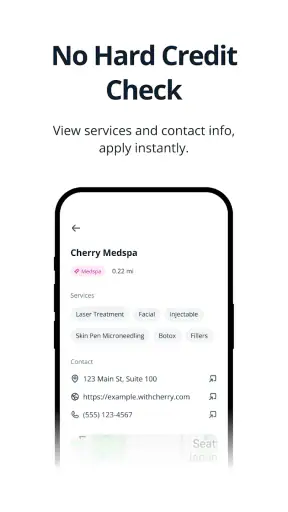
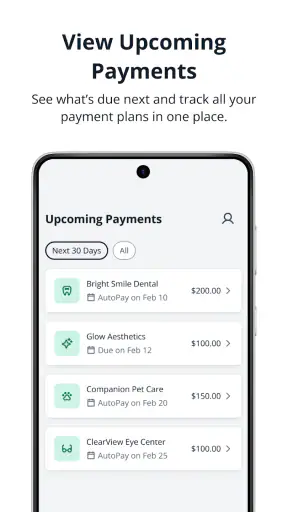
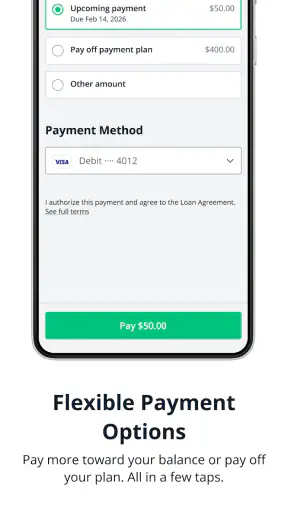
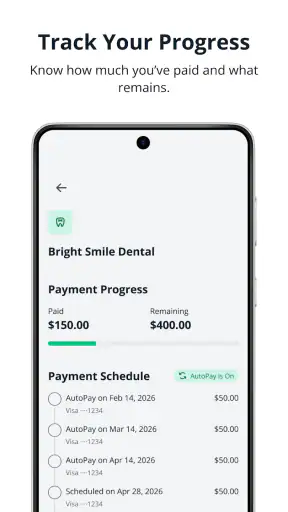
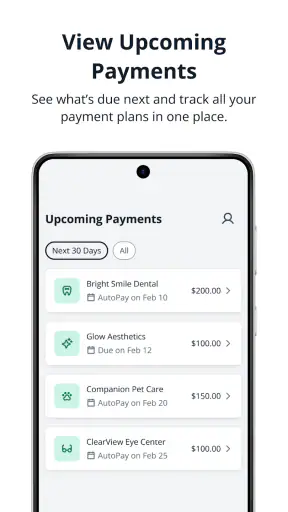
Details
- Rating
- 50.00 reviews
- Version
- 1.3.0
- Developer
- Cherry Technologies, Inc.
Analysis by Norviv
I approached Cherry as a practical finance app rather than something to open only when a payment is already overdue. Its purpose is straightforward: it helps you manage plans and pay on a schedule, with the goal of making repayment easier to organize around normal spending habits. After using it, my impression is that its value comes less from flashy tools and more from giving planned payments a clearer place in your routine.
That distinction matters. Cherry is not trying to be a complete banking replacement, a budgeting spreadsheet, or a broad financial education platform. It is a focused app from Cherry Technologies, Inc. for people who want a more manageable way to keep track of payment plans. The app is free, rated for Everyone, and available for devices running Android 7.0 or later. Its current version is 1.3.0, and it has already passed the 100K-install mark.
I found the best results came from treating it as a small financial habit. Instead of checking it randomly, I used it at predictable moments: when reviewing upcoming expenses, after setting up a plan, and before deciding whether a purchase would fit comfortably into the next few payment periods. That approach made the app feel more useful than simply opening it whenever I remembered it existed.
How the everyday payment workflow feels
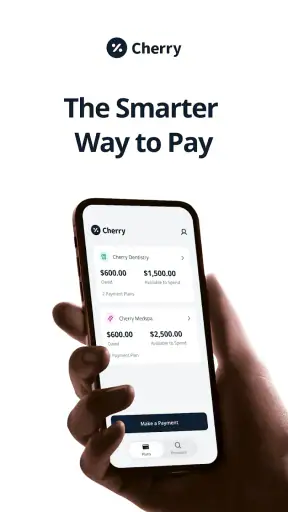
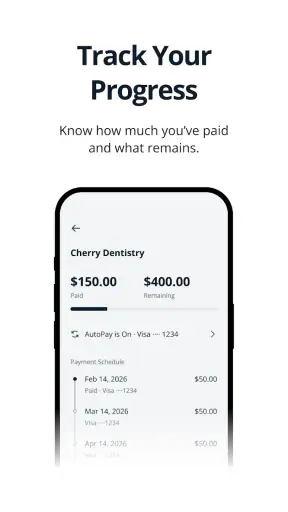
The basic workflow is easy to understand. You use Cherry to keep your plans in view, check what needs attention, and make payments according to a schedule that fits your situation. The app’s store summary, “Manage your plans and pay on your schedule,” describes the central idea accurately, but the practical benefit is in reducing the need to reconstruct your obligations from memory.
For a first-time user, I would begin by reviewing every plan currently shown rather than immediately focusing on the next payment. Look at the overall arrangement, identify which commitments are regular, and separate a plan that needs frequent attention from one that can be checked less often. This first pass creates a personal map of the app and prevents the common mistake of treating every payment as equally urgent.
A realistic example would be a month in which several ordinary expenses arrive close together. Instead of waiting until the busiest week, I would open Cherry during a quieter part of the month, review the relevant plan, and decide what amount can be handled without disrupting essentials. The advantage is not that the app makes the obligation disappear; it gives the obligation a visible place in a repeatable review routine.
I also recommend checking the schedule before making a new discretionary purchase. This is a small but useful change in behavior. Many people think about affordability only at the moment of purchase, while a payment-plan app is more helpful when it is used before that decision. Seeing existing commitments together can make a tempting purchase feel less isolated and encourage a more realistic choice.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
The interface is most useful when you keep your attention on the next action. If a plan needs a payment, deal with that first. If it only needs monitoring, leave it alone and move to the next item. This sounds simple, but it prevents repeated browsing through the same information and makes short check-ins more effective.
One habit I found valuable was pairing Cherry with an existing weekly money check. I did not create a complicated finance ritual. I simply chose one regular day to review plans, then used the app as the payment-plan part of that review. This makes the app easier to remember and reduces the risk of opening it only after a reminder or problem has already appeared.
Cherry works especially well for users who prefer a focused tool over a crowded financial dashboard. If you already know where your money goes but need help keeping scheduled payments organized, the narrow purpose is a strength. You are not forced to sort through unrelated charts, investment screens, or broad account-management features before reaching the information that matters.
At the same time, that focus creates an important boundary. I would not use Cherry as my only method for understanding total household finances. A payment schedule does not automatically replace a full budget, an emergency-fund plan, or a record of spending across accounts. I still prefer a separate budgeting method when I need to examine income, categories, savings, and long-term goals together.
What I would check before relying on it
Before making Cherry part of a serious payment routine, I would confirm that the plans displayed in the app match the arrangements I actually intend to manage. This is not a criticism of the app; it is a sensible financial safeguard. A schedule is only useful when the user enters or reviews it carefully. Take a moment to compare the app’s information with the original agreement or payment details you are working from.
I would also make sure the payment date works with my personal cash-flow pattern. A date that looks reasonable on paper can be uncomfortable if income arrives later or if several household bills are concentrated in the same week. Cherry can help you organize a schedule, but it cannot decide whether that schedule is safe for your wider finances. That judgment remains yours.
Another practical question is whether you want a dedicated payment tool or a single app for everything. If you like separate tools with clear jobs, Cherry is easy to understand. If you expect one application to combine plan management, detailed expense tracking, account balances, and long-term financial planning, you may find its focused approach too limited.
Settings and habits that make the app easier to use
The first settings-related habit I recommend is reviewing the app after installation instead of accepting every default without thought. The exact options available can depend on the device and the version in use, so I would pay attention to how Cherry presents schedules, reminders, and payment information on your phone. The goal is to make the app fit your routine, not to create more notifications than you can act on.
Notifications are most useful when they support a decision. If you receive too many prompts, they can become background noise and eventually be ignored. I prefer a smaller number of meaningful reminders paired with a regular manual review. That combination gives me an early nudge without making the app feel demanding throughout the day.
It is also worth checking whether the app opens to the information you use most often. If the first screen gives you a useful overview, make a habit of starting there and moving directly to the plan that needs attention. If you find yourself repeatedly searching for the same details, change your routine rather than tapping through every section each time. Experienced use is often about reducing unnecessary steps.
Keep the application updated when a new version is available, especially because Cherry is still a relatively focused product. The version I reviewed is 1.3.0, and staying current is a sensible way to benefit from refinements without assuming that an older installation will behave exactly like the current one. Updates are also a good moment to revisit your workflow and check that your important plans still look the way you expect.
Privacy and device security deserve attention with any finance app. I would use a screen lock on the phone, avoid leaving financial information visible in public, and think carefully before sharing screenshots that show plan details. These are user-side habits, but they matter because convenient access should not mean careless exposure.
I would not treat the presence of a payment plan in Cherry as proof that the plan is automatically affordable. The app can make an arrangement easier to see and manage, but it cannot account for an unexpected repair, a change in income, or another obligation unless you consider those factors yourself. My preferred workflow is to review the app alongside a quick check of available cash and upcoming essentials.
Small routines that save time
The fastest approach is to create a short sequence and repeat it. I would open the app, review the overview, inspect the next relevant plan, confirm the intended payment action, and close it. Avoid turning every check into a full financial audit. A concise routine makes it more likely that you will use Cherry consistently, which is more valuable than an elaborate process you abandon after a week.
Another useful pattern is separating “review” from “decision.” During a normal check, gather the information first. Then decide whether to make a payment, adjust your timing, or wait for a better moment to examine the situation. This prevents rushed decisions made simply because the app is open and keeps the tool in its proper role as an organizer rather than a source of pressure.
I also like using a calendar habit outside the app as a backup memory aid. This does not duplicate Cherry’s purpose; it reinforces it. A recurring personal reminder to review plans can be helpful if you are the kind of person who forgets to open finance apps. The app holds the relevant plan information, while the calendar habit gets you to the right place at the right time.
For people managing more than one plan, I suggest reviewing them in the same order every time. Start with the nearest action, then move through the remaining plans in a consistent sequence. This makes it easier to notice changes and reduces the chance of overlooking an item simply because the order of attention keeps changing.
A less obvious benefit of this method is that it helps distinguish administrative stress from actual financial difficulty. Sometimes the problem is not the number of obligations but the effort required to remember them. Organizing them in one focused app can reduce that mental load. If the numbers themselves are unsustainable, however, better organization will reveal the issue rather than solve it.
Where Cherry is strong and where its limits show
Cherry’s strongest quality is clarity of purpose. It is built around plans and scheduled payments, so it can be more comfortable than a general banking app when your main concern is staying oriented around those commitments. I would recommend it to someone who wants a dedicated place to review payment plans without adopting a full personal-finance system.
The app is also approachable for a broad audience. Its Everyone age rating reflects that it is not presented as a specialized professional finance tool. A user who is comfortable with ordinary mobile apps should be able to understand the central workflow without needing financial terminology or technical knowledge.
Its free price makes experimentation easier. You can try the workflow without committing money to another subscription, which is useful when you are unsure whether a dedicated plan-management app will become part of your routine. Free does not automatically mean complete, though, so I would judge it by whether it handles your specific payment habits rather than by expecting it to replace every financial tool you use.
The main limitation is scope. Cherry is not the right choice if your priority is detailed spending analysis, investment management, tax preparation, or a complete household budget. A traditional banking app may be better for checking account balances and transactions, while a budgeting app may be stronger for category-based planning. Cherry makes the most sense when scheduled plans are the problem you are trying to solve.
I would also avoid using it as a substitute for reading the terms of an agreement. The app can help you keep track of a plan, but the original terms remain important. Before relying on any schedule, make sure you understand the amount, timing, and consequences connected with the arrangement you are managing. Good organization supports informed decisions; it does not replace them.
There is another trade-off for advanced users. People who enjoy building detailed spreadsheets may find Cherry less flexible than a system they control themselves. A spreadsheet can combine payment plans with income forecasts, custom categories, savings targets, and unusual scenarios. Cherry is more convenient for a focused daily workflow, but less suitable when you want to model every possible financial variable in one place.
Its audience is reflected in its early but meaningful adoption: the app has an average rating of 4.5 from around 130 ratings and has attracted about 50 written reviews. I see that as encouraging rather than conclusive. It suggests that the focused concept is resonating with users, while the relatively modest review volume means I would still evaluate it against my own routine instead of assuming it will suit everyone.
Who should use it and who should skip it
I think Cherry is a good fit for someone who has one or more payment plans and wants a simple way to keep them visible. It is particularly appealing if you tend to forget dates, dislike navigating a large banking application, or want a dedicated check-in before making new purchases. It can also help people who are building a more deliberate relationship with scheduled payments for the first time.
I would be more cautious about recommending it to a user who needs a complete financial command center. If you want automatic analysis of every transaction, detailed reports, investment views, or extensive customization, a broader finance platform will probably serve you better. Cherry’s simplicity becomes a limitation when your needs extend well beyond plan management.
I would also skip it if you are looking for an app to make financial decisions for you. The useful work here is organizing information and supporting a payment habit. The app cannot tell you whether taking on another obligation is wise in the context of your income, savings, and other bills. Users who want automated financial coaching may prefer a different category of tool.
For families, the decision depends on how responsibilities are shared. If one person handles the plans, a focused app can make that task easier to review. If several people need simultaneous visibility and a shared household budget, you may need a broader system with stronger collaboration features. I would decide based on who needs to act, not simply on how many plans exist.
My verdict after building a repeatable routine
Cherry is at its best when I use it deliberately: review plans on a regular day, check the next action before spending, keep reminders useful, and treat the app as one part of a larger financial routine. That combination turns a simple payment organizer into a practical habit tool. The value is not in opening it constantly; it is in knowing exactly when to open it and what to do there.
I appreciate that the app does not need to be complicated to be useful. Its focused approach can be less intimidating than a full finance suite, and the free price lowers the barrier to trying it. The developer, Cherry Technologies, Inc., has positioned the product around a clear everyday need, and the current version gives users a straightforward starting point for managing plans on a schedule.
My reservations are equally clear. Cherry cannot replace a budget, a bank account overview, or careful reading of payment terms. Users with complex financial planning needs may outgrow its focused workflow, while users who want extensive customization may prefer a spreadsheet or a broader finance application. Those are not failures so much as boundaries that should be understood before making the app central to your money management.
For me, the deciding question is simple: do you need help remembering and organizing payment plans, or do you need a complete picture of your finances? If it is the first, I think Cherry is worth trying as a focused finance companion. If it is the second, use it only as one layer alongside a fuller budgeting method.
Overall, I would recommend it to a friend who wants less friction around scheduled payments and is willing to maintain a small, repeatable review habit. The best results come from combining the app with personal discipline: check plans before commitments, keep reminders manageable, and confirm that every payment fits your wider situation. Used that way, Cherry is modest in scope but genuinely practical.
Frequently Asked Questions
01What is Cherry: The Smarter Way to Pay?
Cherry is a healthcare financing and payment platform that allows eligible patients to split the cost of certain medical, dental, cosmetic, and wellness treatments into scheduled payments. Instead of paying the full amount upfront, you can apply through a participating provider, review the available payment options, and choose a plan that fits your budget. Availability depends on the clinic, your application details, and approval terms.
02How does the Cherry payment application process work?
To use Cherry, you generally begin with a participating healthcare provider and request financing for an eligible treatment. You may be asked to provide personal and financial information so Cherry can assess your application. If approved, the available plans, payment amount, schedule, and applicable terms are shown before you accept. Read the agreement carefully, because approval and payment conditions can vary between users and providers.
03Does using Cherry affect my credit score?
Cherry may use credit-related information as part of its application and approval process, but the exact impact can depend on the type of inquiry, your circumstances, and the financing product offered. The app or provider should explain any relevant credit checks and reporting practices before you agree. If your credit history is important to you, review the disclosures and terms rather than assuming every application works the same way.
04What treatments and providers accept Cherry?
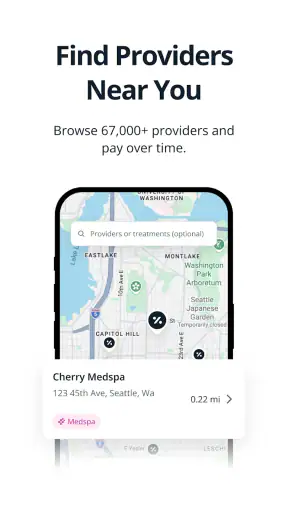
Cherry is not accepted by every healthcare business, and eligible services can differ from one provider to another. It is commonly associated with services such as dentistry, cosmetic procedures, elective healthcare, and wellness treatments, but the provider determines which procedures qualify. Before downloading or applying, confirm that your chosen clinic works with Cherry and ask whether the specific treatment, deposit, or remaining balance can be financed.
05Are there fees, interest, or other conditions with Cherry plans?
Payment plans can have different costs and conditions, including interest, promotional terms, late-payment consequences, administrative charges, or other fees depending on the offer and provider. The most important details are displayed in the financing agreement before acceptance, so check the total repayment amount rather than focusing only on the monthly payment. Also verify what happens if treatment is canceled, refunded, delayed, or changed.


